Have You Checked What Happens to Your Health Insurance Benefits in January?
Before the calendar flips to 2027, here’s what to know about your physical therapy coverage, deductibles, copays, and out-of-pocket costs.
It’s November. The holidays are approaching, your calendar is filling up, and somehow another year is almost over.
But there’s one thing you might want to check before January 1: your health insurance benefits.
If you’ve been putting off physical therapy for that nagging knee pain, stiff shoulder, recurring back pain, or dizziness that just won’t go away, the end of the year is a good time to take a closer look at your insurance coverage.
Why? Because many health insurance plans reset their deductibles and out-of-pocket maximums at the beginning of a new plan year. If you’ve already met your deductible in 2026, your costs for covered healthcare services could look very different once January arrives.
And if you’ve been meaning to schedule physical therapy, understanding your benefits now could help you make a more informed decision about when to start.
Let’s break it down.
1. Does Your Health Insurance Deductible Reset in January?
For many people, yes!
Most health insurance plans operate on a calendar-year basis, meaning your deductible resets on January 1.
Your deductible is the amount you pay toward covered healthcare services before your insurance begins sharing costs according to your plan.
Here’s a simple example:
Imagine your health insurance plan has a $2,000 annual deductible.
- In January, you start the year with $0 applied toward your deductible.
- Throughout the year, you pay for covered healthcare services.
- By November, you’ve paid $2,000 toward your deductible.
- You’ve now met your deductible for 2026.
Depending on your plan, you may now be responsible for only a copay or coinsurance for additional covered services.
But when January 1, 2027 arrives, that deductible could reset to $2,000 all over again.
That means you may be back to paying toward your deductible before your insurance starts sharing costs.
Why this matters for physical therapy: If you’ve already met your deductible this year, your out-of-pocket cost for a physical therapy visit could be different in December than it is in January.
It’s worth checking before assuming your costs will stay the same.
Important: Not every plan follows a January-to-December benefit year. Some employer-sponsored plans have different renewal dates, and individual plan rules vary.
2. What Happens to Your Out-of-Pocket Maximum?
Your deductible isn’t the only number worth checking.
Your out-of-pocket maximum is the most you pay during a benefit year for covered services subject to that limit. Once you’ve reached it, your insurance generally pays 100% of covered, in-network services for the remainder of that benefit year.
Let’s say your out-of-pocket maximum is $5,000.
By December, you’ve paid enough toward covered healthcare expenses to reach that $5,000 limit.
For the rest of your plan year, you may have little or no additional cost-sharing for covered, in-network services.
Then January arrives, and your plan year starts over.
Your out-of-pocket maximum may reset, too.
The takeaway: If you’ve had surgery, seen specialists, completed imaging, or had several medical appointments this year, you may be closer to your out-of-pocket maximum than you realize.
Before scheduling your next appointment, check where you stand.
3. Could Physical Therapy Cost More in January?
It could, depending on your insurance plan.
Physical therapy costs aren’t the same for everyone. Your out-of-pocket responsibility may depend on:
- Whether you’ve met your annual deductible.
- Whether you have a copay or coinsurance for outpatient physical therapy.
- Whether your physical therapist is in-network.
- Whether your plan requires a referral or prior authorization.
- Whether you have an annual visit limit or other coverage restrictions.
For example, let’s compare two hypothetical patients with the same insurance plan.
Patient A: Starting PT in December
They’ve already met their annual deductible and have a $30 physical therapy copay.
Their covered in-network PT visit may cost them $30.
Patient B: Starting PT in January
They have the same insurance plan, but their deductible has reset.
They may need to pay the contracted cost of their covered PT visits until they meet their deductible, depending on their plan’s benefits.
Same insurance company. Same physical therapy clinic. Potentially very different out-of-pocket costs.
This is why we encourage patients to understand their benefits before the new year rather than being surprised by their first healthcare bill in January.
4. What If You’ve Been Putting Off Physical Therapy?
We get it. Life gets busy.
Maybe your shoulder has bothered you for months, but it’s manageable. Your back gets sore after sitting at work, but you keep pushing through. Your knee hurts when you hike, but you don’t want to give up your weekend plans.
It’s easy to convince yourself that you’ll deal with it later.
But pain that keeps interfering with your everyday activities deserves attention.
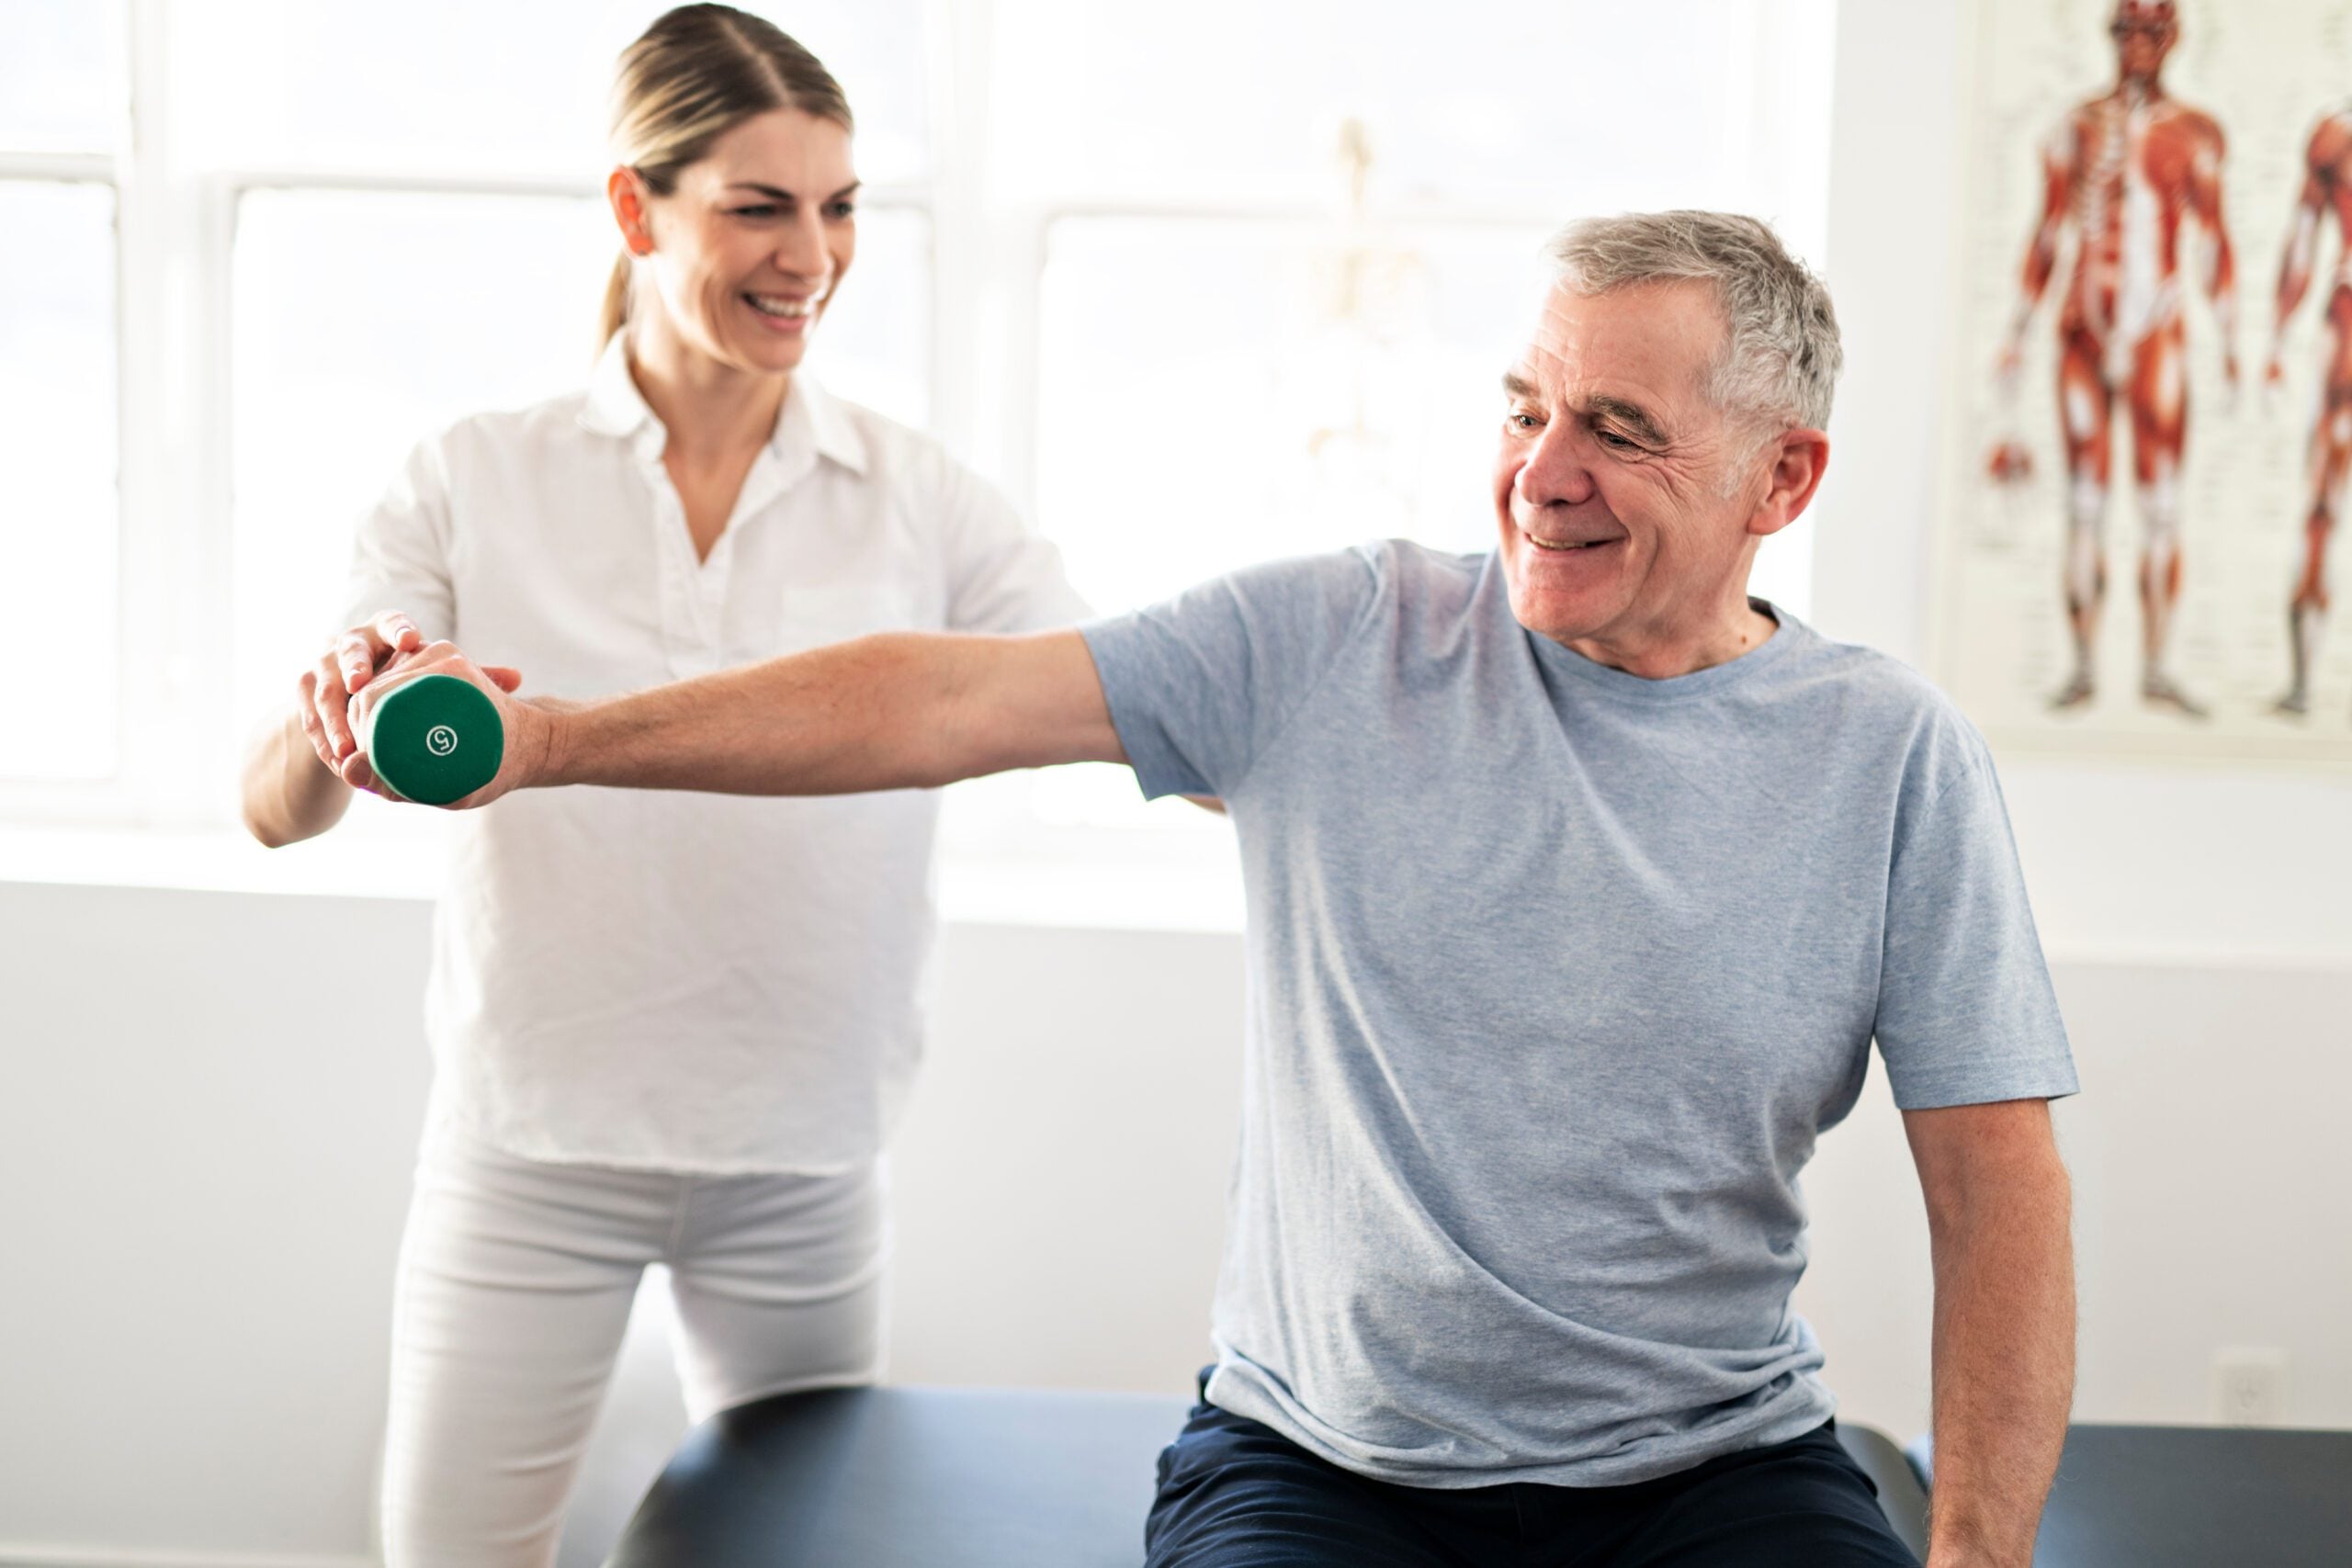
Physical therapy can help you address the underlying factors contributing to pain and movement limitations, build strength, improve mobility, and return to the activities you enjoy.
And you don’t necessarily need months of treatment before you start making progress.
In fact, our previous article explores what you could accomplish in your first four physical therapy visits, including improvements in movement, strength, and everyday function.
If something has been bothering you for weeks or months, consider making a plan to address it before another year goes by.
5. What Happens If You Have New Health Insurance in 2027?
Are you changing employers, switching insurance plans, or enrolling in a new policy for next year?
If so, don’t assume your new coverage will work exactly like your current plan.
Even if you stay with the same insurance company, your benefits could change.
Before scheduling physical therapy in 2027, check:
- Is outpatient physical therapy covered?
- Is your physical therapy clinic in-network?
- Does your plan have a separate deductible for individual and family coverage?
- Do you have a copay or coinsurance for PT?
- Is there a limit on the number of physical therapy visits?
- Do you need a referral or prior authorization?
- Does your new plan require you to use a specific provider or network?
A quick phone call to your insurance company can save you from unexpected costs later.
Also, remember that having an insurance card with the same company name doesn’t necessarily mean you have the same benefits or network.
6. Five Questions to Ask Your Insurance Company Before Scheduling Physical Therapy
Not sure what to ask? Keep this list handy when you call the member services number on the back of your insurance card.
1. Have I met my annual deductible?
Ask how much of your deductible you’ve already satisfied and how much you have remaining for 2026.
2. What Is My Out-of-Pocket Maximum, and How Much Have I Paid Toward It?
This can help you understand whether you’re close to reaching your annual limit.
3. What Is My Copay or Coinsurance for Outpatient Physical Therapy?
Be specific. Ask about outpatient physical therapy, not just specialist visits.
4. Do I Have a Limit on the Number of Physical Therapy Visits?
Some plans have annual visit limits or additional requirements for continued treatment.
5. Does My Plan Require a Referral or Prior Authorization?
This is especially important if you have Medicare, Medicaid, or a plan with specific referral requirements.
One more tip: Ask your insurance company to explain whether your benefits reset on January 1 or on a different plan-year date.
7. How Epic Physical Therapy Can Help You Understand Your Options
If you’re looking for physical therapy in South Denver, Epic Physical Therapy is here to help.
We’re a locally owned, physical therapist-owned and operated practice with convenient locations in Greenwood Village and Highlands Ranch.
We believe getting physical therapy shouldn’t feel like another complicated item on your to-do list.
Our team works with many major insurance plans, including:
- Kaiser Permanente
- Medicare
- Medicaid / Health First Colorado
- Blue Cross Blue Shield
- UnitedHealthcare
- Cigna
- Workers’ Compensation
- Many other commercial insurance plans
Not sure if we accept your insurance? Just ask!
Our front desk team can help verify your benefits and explain the information available to us before your first appointment.
A quick reminder about referrals:
- Kaiser Permanente: Epic PT does not require a provider referral for our Kaiser patients. We do need your Kaiser subscriber ID to verify coverage.
- Medicare: A referral or order from your medical provider is required.
- Medicaid: A referral from your established healthcare provider is required. Our team can often help coordinate this with your provider’s office.
- Other commercial plans: Referral and authorization requirements vary by policy.
Insurance verification is not a guarantee of payment, so we always recommend confirming your specific coverage with your insurance company as well.
Why South Denver Patients Choose Epic PT
At Epic PT, we don’t believe in handing everyone the same sheet of exercises and sending them on their way.
We take the time to listen, understand your goals, and create a treatment plan that makes sense for you.
Our approach combines hands-on manual therapy with skilled therapeutic exercise to help patients:
- Reduce back, neck, shoulder, hip, and knee pain.
- Recover from sports and work-related injuries.
- Improve balance and address dizziness or vertigo.
- Recover after surgery.
- Build strength and mobility.
- Return to running, golfing, hiking, pickleball, and other activities.
You’ll work directly with a licensed physical therapist throughout your care, not a rotating team of assistants.
We also offer complimentary 30-minute consultations for people who want to talk with a physical therapist about their symptoms and determine whether PT is a good fit.
8. Don’t Let Another Year Go By Putting Off Your Pain
Here’s something to think about as you head into 2027:
Your deductible might reset. Your insurance benefits might change. Your healthcare costs could look different.
But that shoulder pain you’ve been ignoring? That knee that hurts every time you take the stairs? That back pain that makes it hard to get comfortable at night?
Those things don’t automatically reset on January 1.
If you’ve been thinking about physical therapy, now is a good time to understand your insurance options and make a plan.
Whether you want to use your remaining 2026 benefits or get a head start on your 2027 healthcare planning, Epic Physical Therapy is here to help.
Let’s make 2027 the year you stop working around your pain and start working toward feeling better.
Schedule a Free Physical Therapy Consultation with Epic PT
Greenwood Village
9250 E. Costilla Ave., Suite 201
Greenwood Village, CO 80112
Phone: 720-572-4873
Highlands Ranch
9088 S. Ridgeline Blvd., Suite 106
Highlands Ranch, CO 80129
Phone: 720-458-0522
Serving Greenwood Village, Highlands Ranch, Littleton, Centennial, Lone Tree, and surrounding South Denver communities.
Same-week appointments available when scheduling permits.
Request an Appointment with Epic Physical Therapy →
Frequently Asked Questions About Physical Therapy and Insurance Benefits
Does health insurance reset on January 1?
Many health insurance plans use a calendar-year benefit period, meaning deductibles and out-of-pocket maximums reset on January 1. However, some employer-sponsored plans use different renewal dates. Check your specific policy to confirm.
Does my physical therapy deductible reset every year?
If your health insurance plan has an annual deductible tied to a calendar-year benefit period, it generally resets on January 1. You may need to meet your deductible again before your insurance begins sharing costs for covered physical therapy services.
Is physical therapy covered by health insurance?
Many health insurance plans cover medically necessary outpatient physical therapy. Coverage, copays, deductibles, visit limits, and referral requirements vary by insurance provider and individual plan.
Is it cheaper to start physical therapy before January?
It can be, especially if you’ve already met your annual deductible or out-of-pocket maximum. However, your actual cost depends on your insurance benefits, provider network, and coverage rules. Ask your insurance company to confirm your estimated costs before scheduling.
Does Epic Physical Therapy accept Kaiser Permanente?
Yes! Epic Physical Therapy works with Kaiser Permanente. Our Kaiser patients do not need a provider referral to begin care at Epic PT. We need your Kaiser subscriber ID to verify your benefits.
Does Epic Physical Therapy accept Medicare and Medicaid?
Yes! Epic PT accepts Medicare and Medicaid. Both require a referral for our services. If you’ve recently seen your established provider, our team can often help coordinate the referral.
Where can I find physical therapy in Highlands Ranch or Greenwood Village?
Epic Physical Therapy has two South Denver locations: one in Greenwood Village near I-25 and Arapahoe Road and another in Highlands Ranch on S. Ridgeline Boulevard. Both offer personalized orthopedic, sports, and vestibular physical therapy.
Can Epic PT check my insurance benefits before my first visit?
Yes! Our front desk team can help verify your insurance benefits, including available information about deductibles, copays, and coverage requirements. We recommend confirming your individual benefits with your insurance company, too, since verification does not guarantee payment.